A Plan Isn’t the Same Thing Every Year
A Medicare Advantage plan isn’t a fixed thing. It’s something a carrier builds, prices, and sometimes adjusts, year over year, and the client sitting across the table is trusting you to know the difference between a change they should expect and one that would catch them off guard.
That carrier is a private insurance company stepping in to deliver Medicare benefits on the government’s behalf, agreeing to cover what Medicare requires and often adding extra benefits on top. That arrangement puts real decisions in the carrier’s hands every year, pricing, networks, what it can afford to offer, and those decisions are what separates a plan that holds up from one that doesn’t.
What Changes From Year to Year, and What Doesn’t
A plan’s costs and benefits for a given year, what a client pays for a doctor visit, their deductible, whether a specific drug is covered, are locked in before that plan year even starts. Each fall, usually in September, members receive an Annual Notice of Change, a letter spelling out exactly what will be different come January. That notice is the only point in the year when those numbers are allowed to move, and it’s why the review conversation belongs in the fall, not March.
Provider networks don’t follow that same calendar. A doctor, clinic, or hospital can leave a plan’s network mid-year, not just at renewal, and while the plan has to notify affected members when that happens, losing a provider doesn’t automatically hand someone the right to switch plans on the spot. Medicare can grant what’s called a Special Enrollment Period if it decides the change is significant enough, though that call gets made case by case. Otherwise, the client waits for the next open enrollment window to move.
You can’t promise a network stays the same forever, no agent can. What you can do is keep your client in the loop, so they know what’s foreseeable and feel comfortable with it before it happens, and that’s often what decides whether they stay with you next year.
Where Judgment Carries Weight
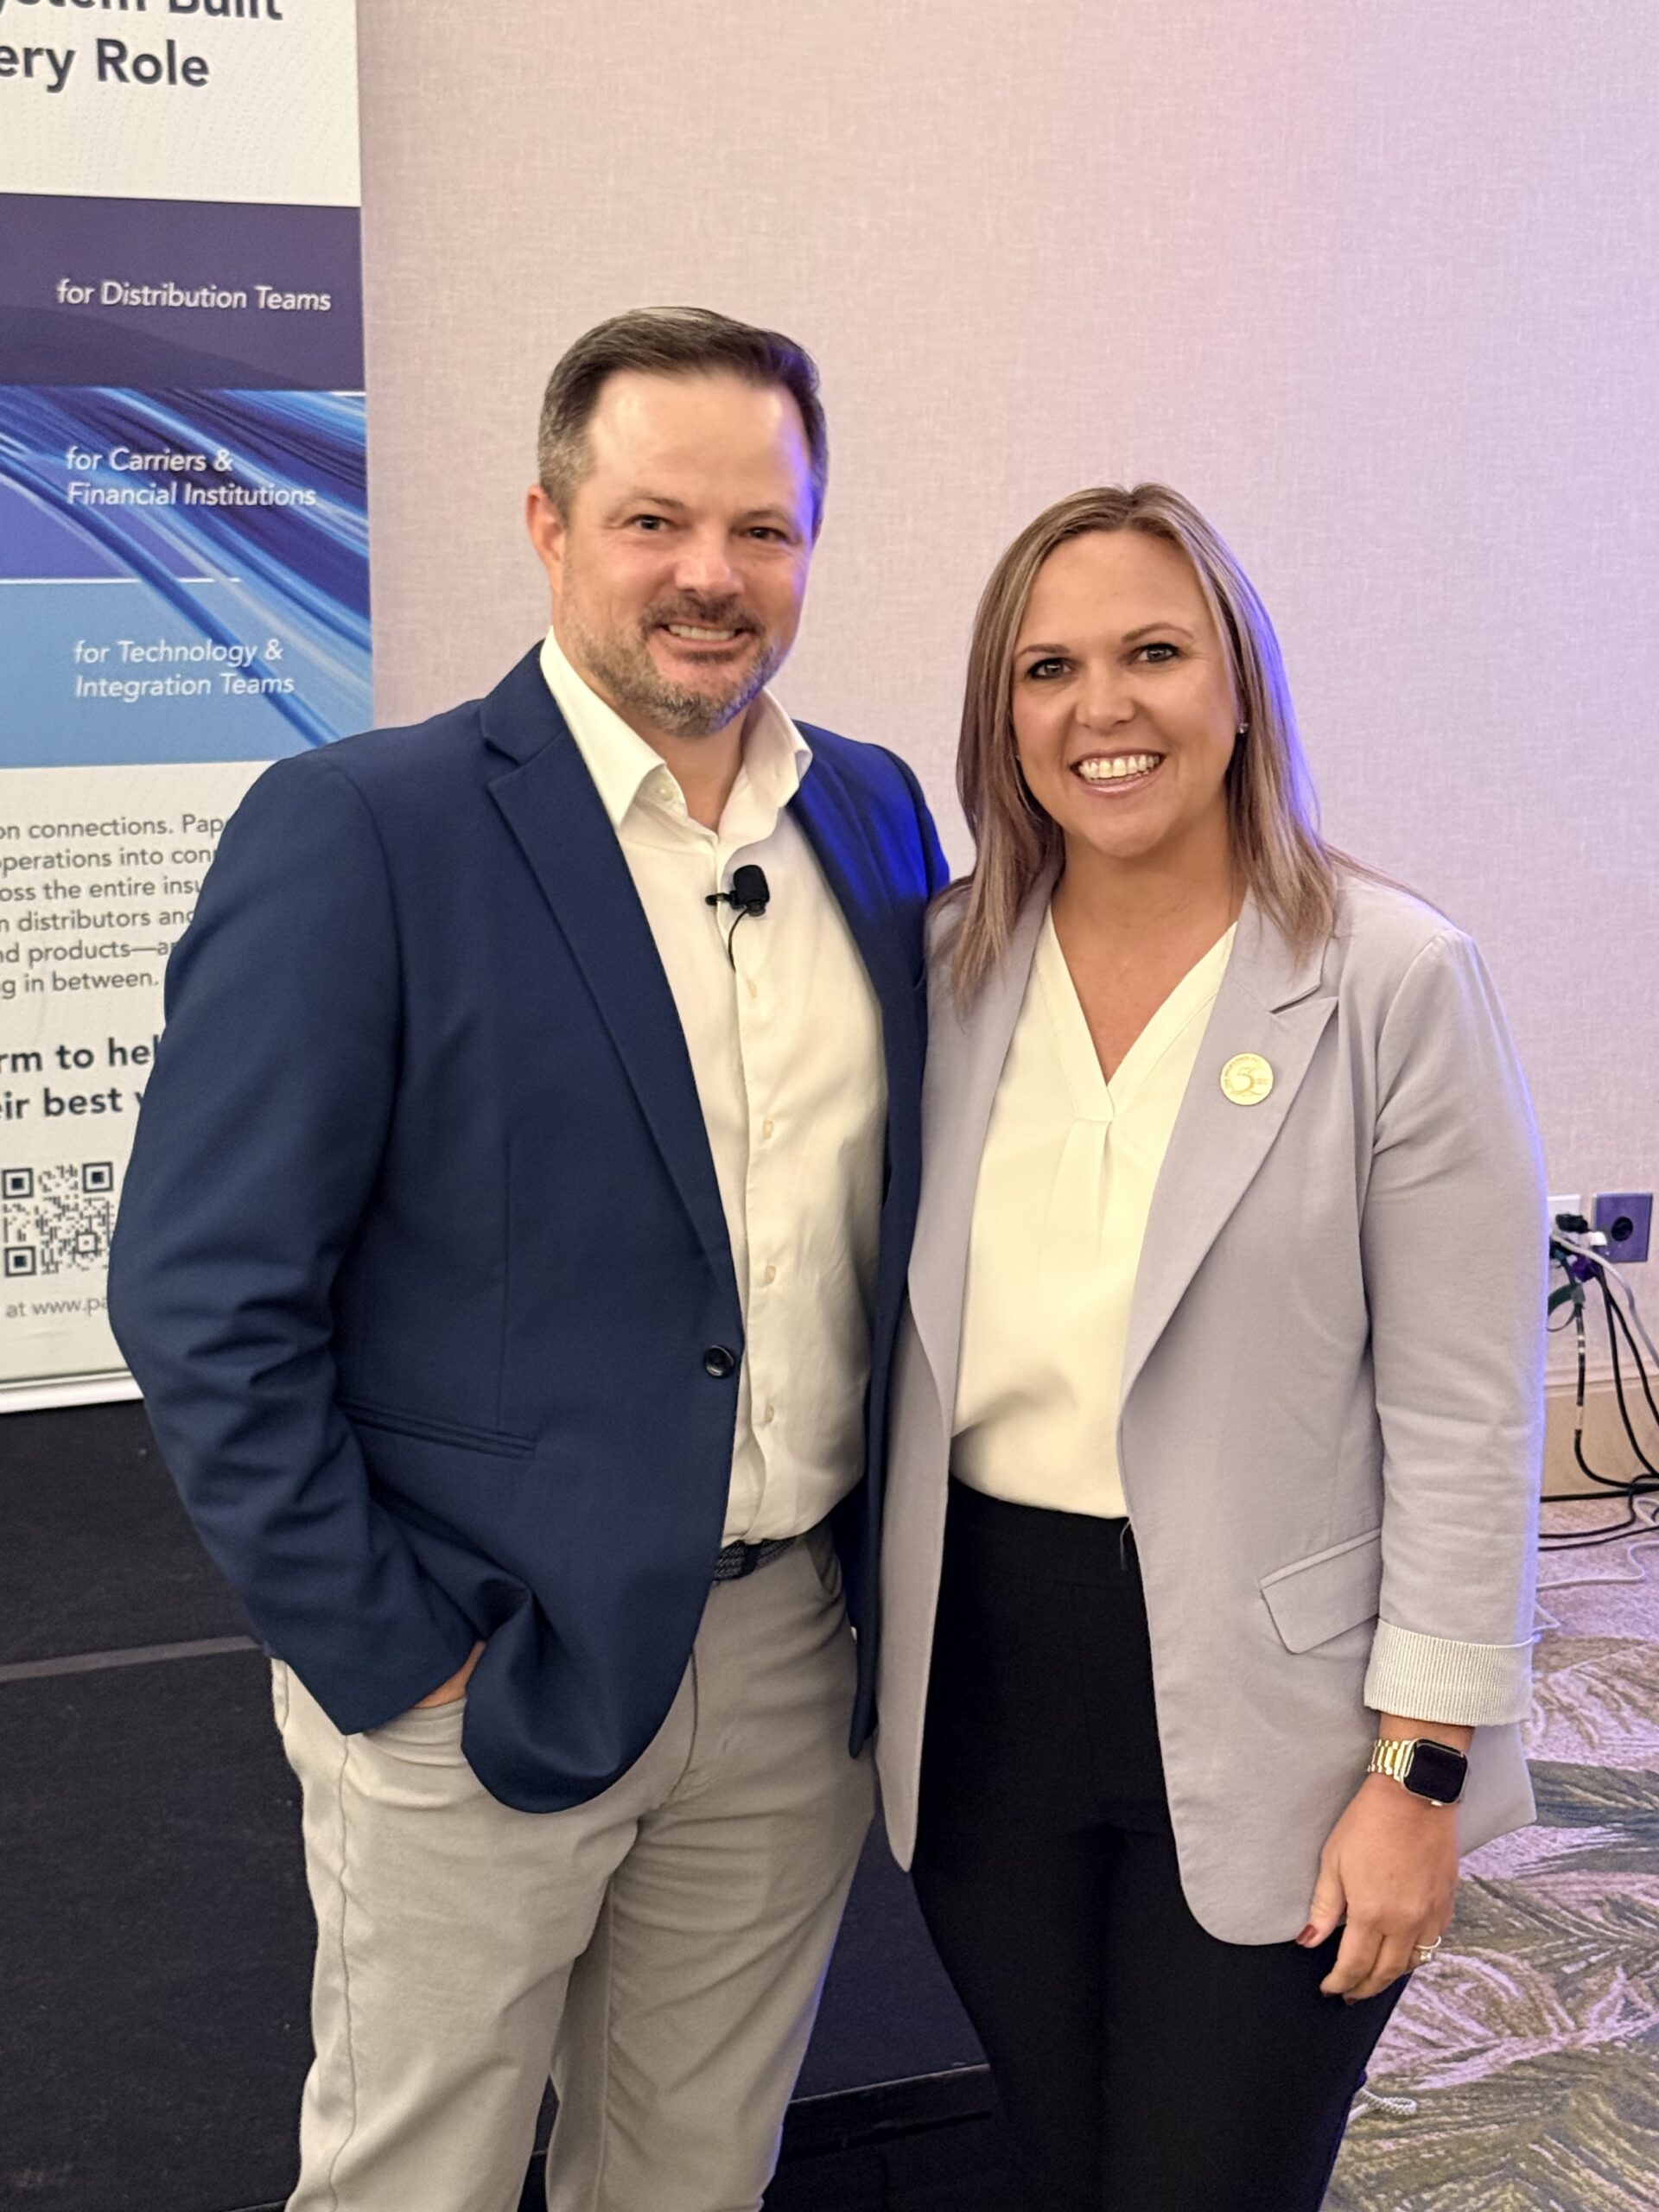
Josh Slattery, Executive Vice President of The Brokerage Inc., has spent time on both the agent and the carrier side over the years, and when he and Elizabeth Davis, VP of National Partnerships at HealthSpring, sat down together on the Broker Link Podcast, he was direct about where that work begins: checking a client’s own doctors and prescriptions against a plan’s network, rather than assuming coverage because the plan has a good local reputation.
The real numbers matter just as much, the ones that shape a client’s year far more than the premium alone:
- What a visit to a primary care provider costs
- What a specialist visit costs
- What a hospital stay costs
- What their prescriptions cost
- What their total out-of-pocket maximum is for the year
Honesty matters just as much as the math. A client should hear plainly what a plan does and doesn’t guarantee, rather than being left to assume more permanence than any plan can offer, and the recommendation itself should follow the client’s doctors, medications, and budget, not whichever plan has the flashiest extra. A grocery allowance or a dental credit can catch someone’s eye at enrollment, but it has nothing to do with whether the plan covers what that client needs. It’s the difference between a client who stays and one who starts shopping around next year.
“We have to get back to focusing on those core medical benefits and not selling the new shiny toy,” Davis said in that same conversation. The primary care copay, the hospital cost, the lab work, the prescription costs, those are what a Medicare Advantage plan exists to cover, and leading with them is what builds something that lasts past a single enrollment season, for the client and for the agent who sold it to them.
The One Thing No Needs Analysis Can Control
Even the best needs analysis can’t control whether a carrier grows faster in a given market than its own network and pricing can support. When that happens, something eventually gives, usually a plan change, a narrower network, or a product that quietly disappears the following year, and this is where the choice of carrier stops being a detail and starts being the whole conversation.
A publicly traded insurance company answers to shareholders and to a quarterly earnings report, and that comes with real pressure. Davis described it plainly: a publicly traded carrier is “beholden to your next quarterly report to Wall Street,” pressure that can push a company toward faster growth just to make a projection look right, whether or not that growth holds up in every market it’s chasing.
HealthSpring answers to something different. It’s the national Medicare brand of Health Care Service Corporation, which describes itself as the largest customer-owned health insurer in the United States, structured as a Mutual Legal Reserve Company, serving roughly 27 million people. It operates under the Blue Cross and Blue Shield name in Illinois, Texas, New Mexico, Oklahoma, and Montana, with no stock to trade and no quarterly earnings call to answer to.
“Every earnings call, they’re under the microscope, subject to Wall Street punishment if they’re not performing as projected,” Slattery said. “Even in times like this, where there’s turbulence in the market, you guys can weather the storm, and you’re able to make business decisions really for the long term.” Davis pointed to where that philosophy shows up day to day: “Every dollar that we’re not spending on our members, in our mind, is a bad dollar spent.”
No carrier, structured any way, can promise a plan never changes or a doctor stays in network forever. What a structure like HealthSpring’s does offer is a company with less reason to outgrow a market faster than it can support, a real, if modest, difference, and one worth knowing before deciding which carriers belong in your book.
Getting Contracted
HealthSpring carries real scale behind that stability. Health Care Service Corporation, the company behind it, runs Medicare Supplement plans in 48 states and the District of Columbia and calls itself the second largest Medicare Supplement carrier by policyholders served, with its Medicare Advantage, Part D, and Medicare Supplement products all now under the HealthSpring name.
What that scale means for you is simpler than it sounds: a wider set of products to build around, backed by a company positioned to keep offering them. The Brokerage Inc. can walk you through what’s open in your market, starting with your Medicare sales representative or the HealthSpring contracting and product resources already waiting in BrokerLink.
Get ContractedListen to the Full Podcast on the Broker Link Podcast
Or Watch on Youtube: